Articles and guides on crypto market data, data quality, and building backtests on clean OHLCV candles.
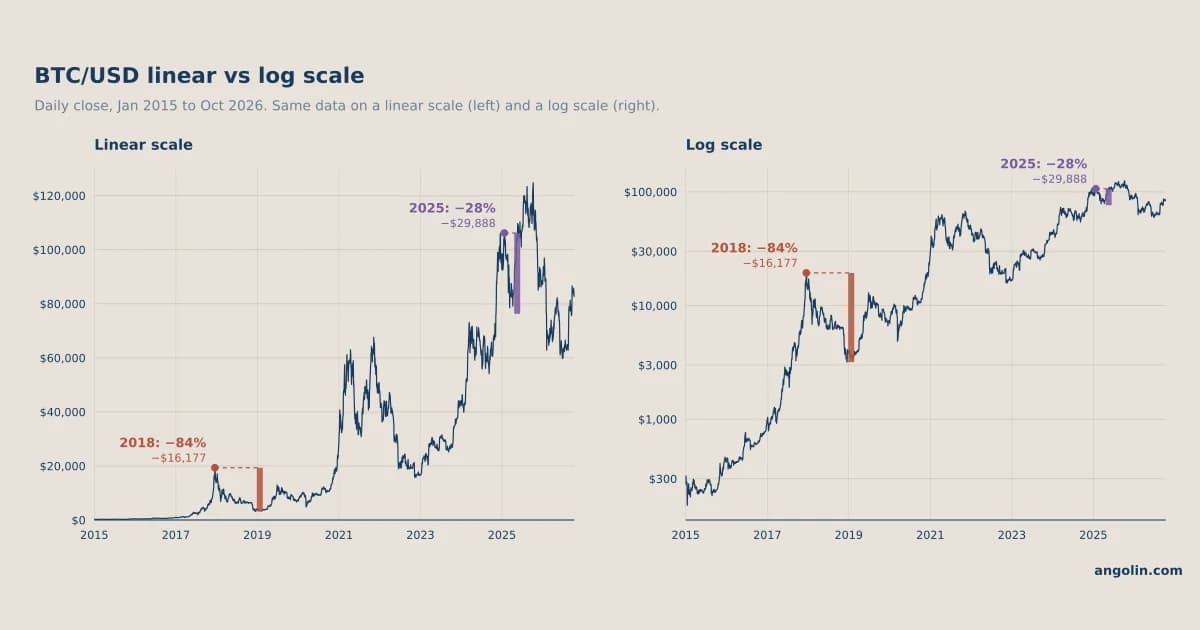
Simple returns are not symmetric, they don't add up over time, and their average flatters volatile assets. Why log returns and log charts are the natural tools to study prices, with BTC as the example.
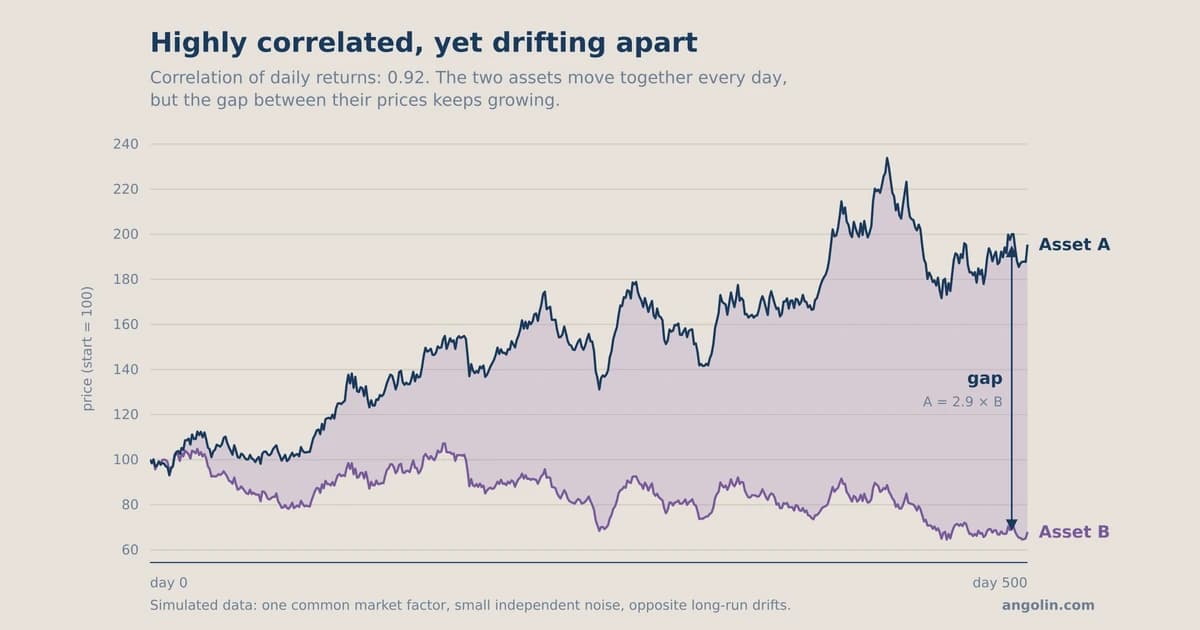
BTC and ETH move together almost every day, yet they are not cointegrated. What the two concepts really mean, why correlation is everywhere in crypto while cointegration is almost nowhere, and what that means for pairs trading.
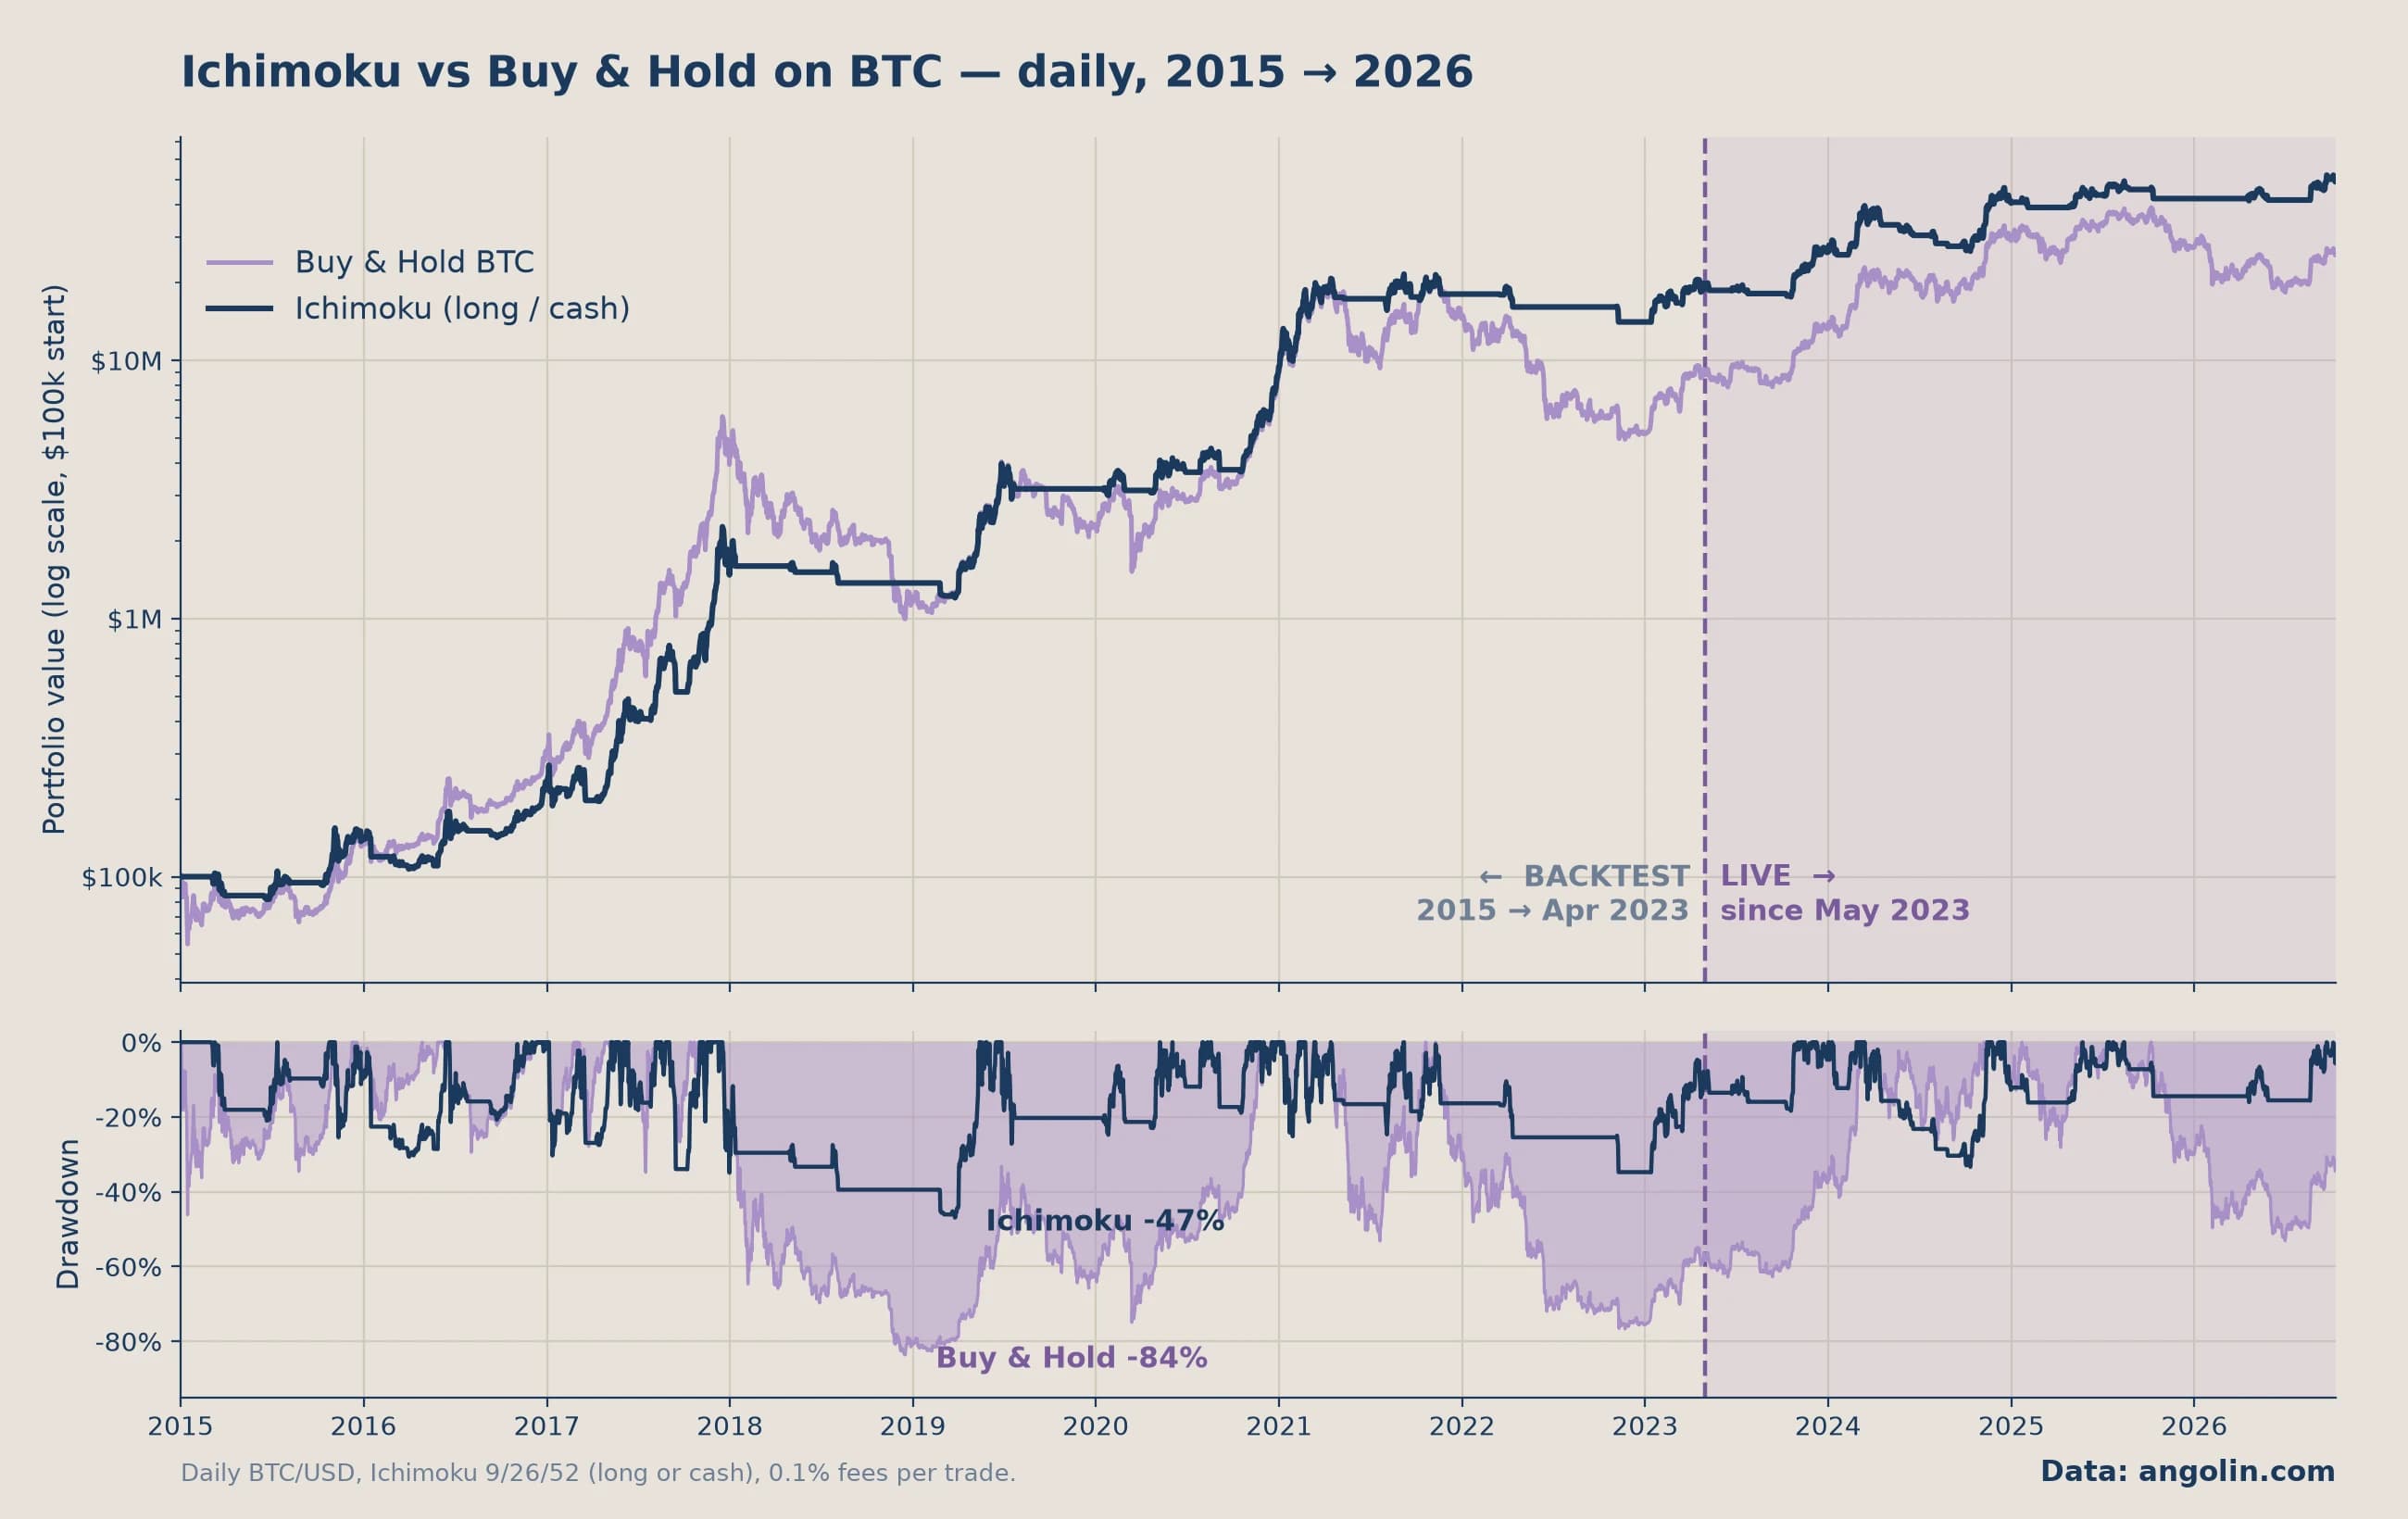
Quants are right about intraday trading. At low frequency it's less clear: you can't statistically prove an edge for years, returns mostly come from factor exposure, and the real risk is quitting during a drawdown.
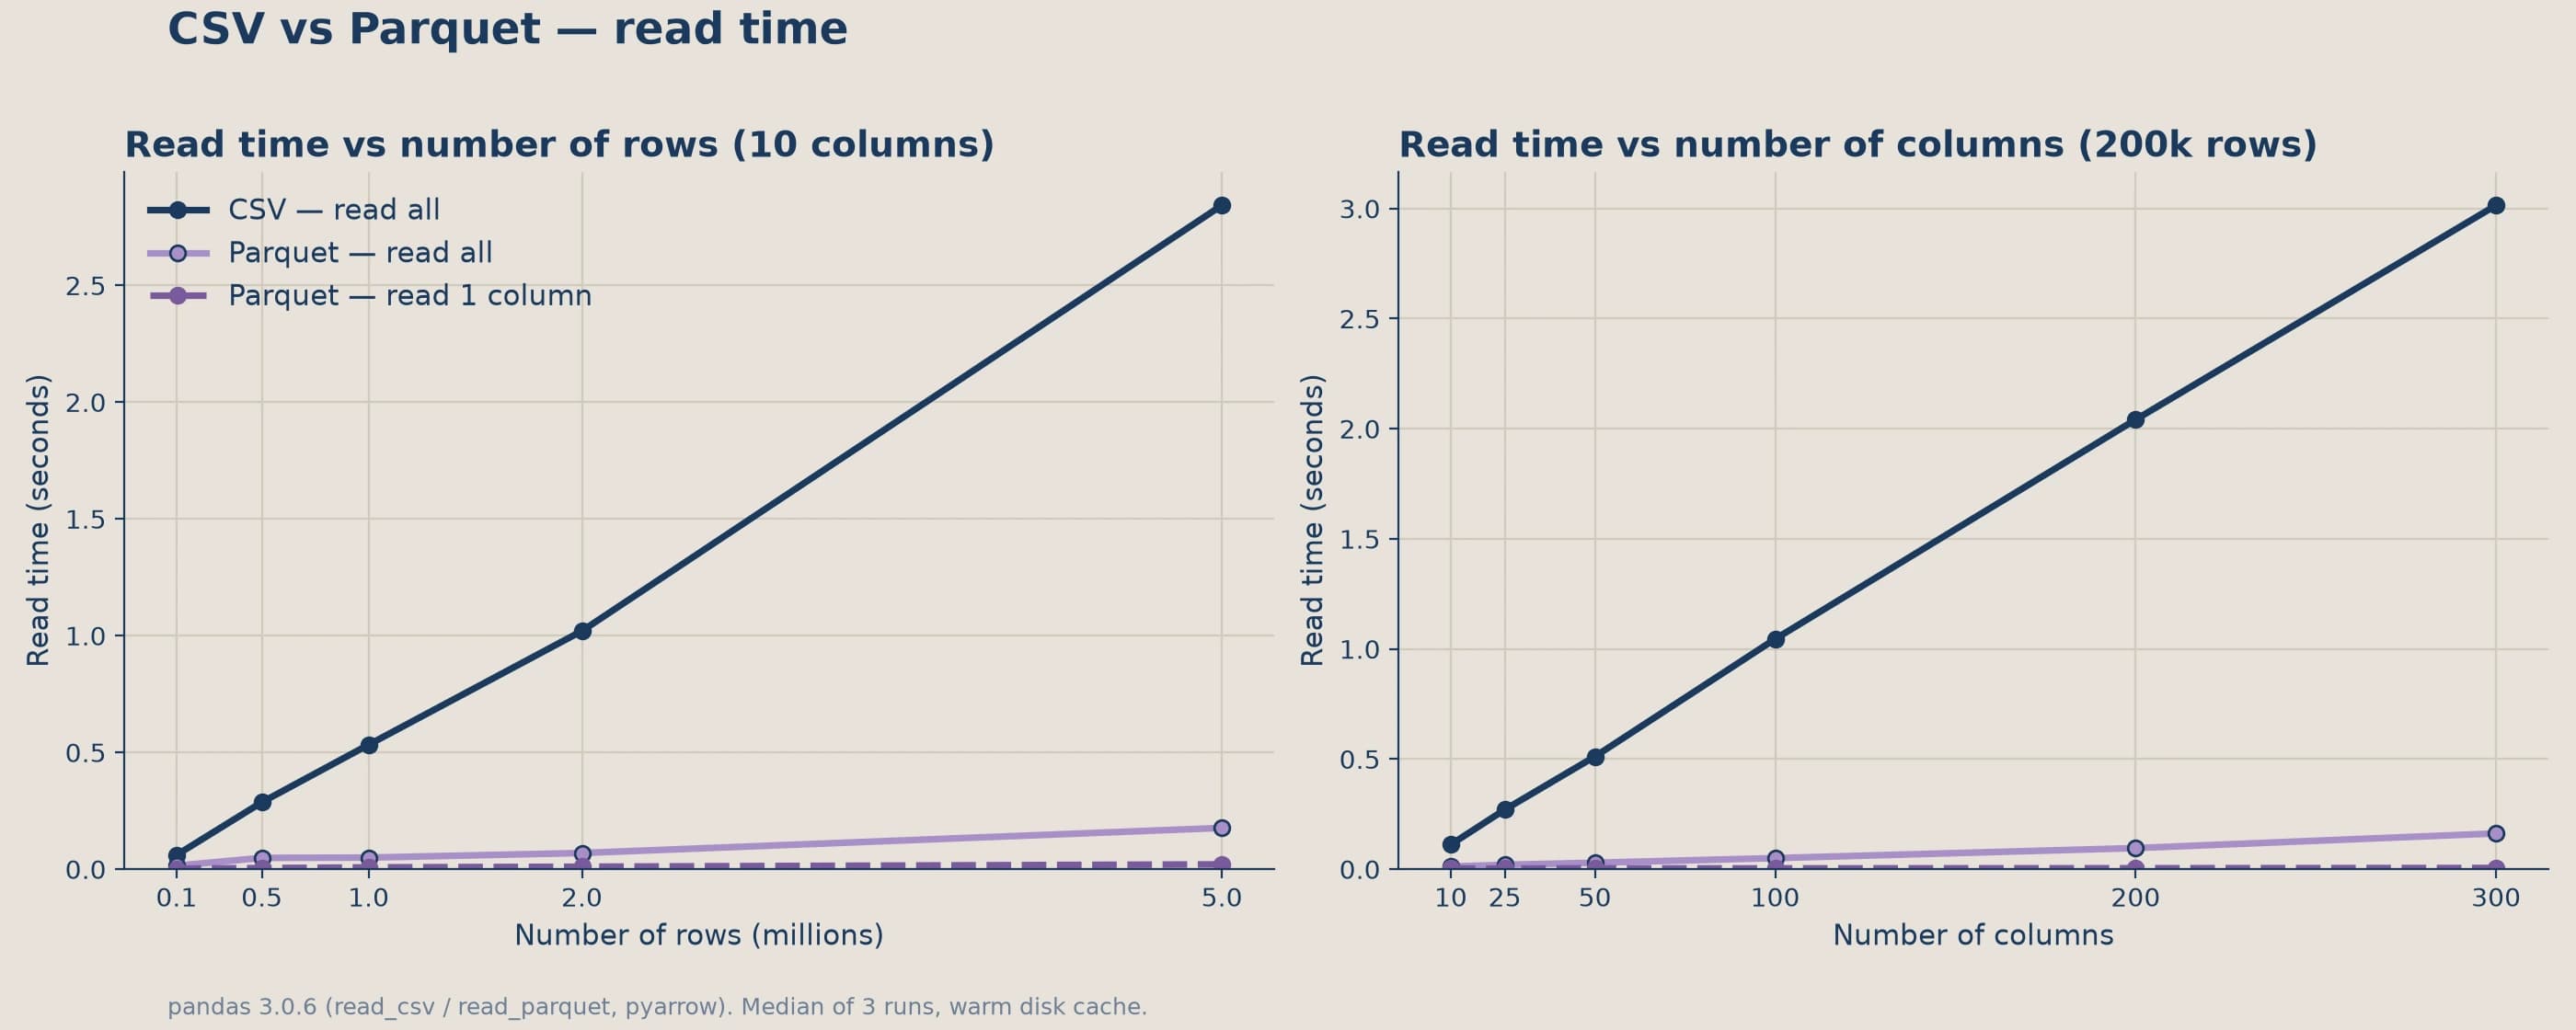
Pandas and CSV are everyone's default for market data, but they don't scale. Parquet and Polars read faster, take less space and use a fraction of the RAM. Here is why, with benchmarks.